

Hello and welcome to the first FASTMaster analysis on March’s available channels. More to come, I’ve just been snowed under with preparing for various panels at conferences I’m moderating (two for TV of Tomorrow, one for the NAB), writing a report for the NAB, presenting to the Caribbean Cable & Telecoms Association on why they should embrace FAST (spoiler: I convinced them) and then everything else in the world. It’s why the FASTMaster podcasts have slowed down too. But I’ll be back later this week with the full report, and then the attrition analysis.
You know the drill: FAST channels continue to grow. It has plateaued in recent months however but slowly is ticking up. Part of the growth this month is down to STIRR’s resurgence, and the rest is down mainly to Sling Freestream once again hoovering up all the Arabic livestreams it can find. That has helped to propel Sling Freestream to the vaunted title of Service with the Most Channels, and quite frankly it wouldn’t be a surprise to see them hit 600 before June.
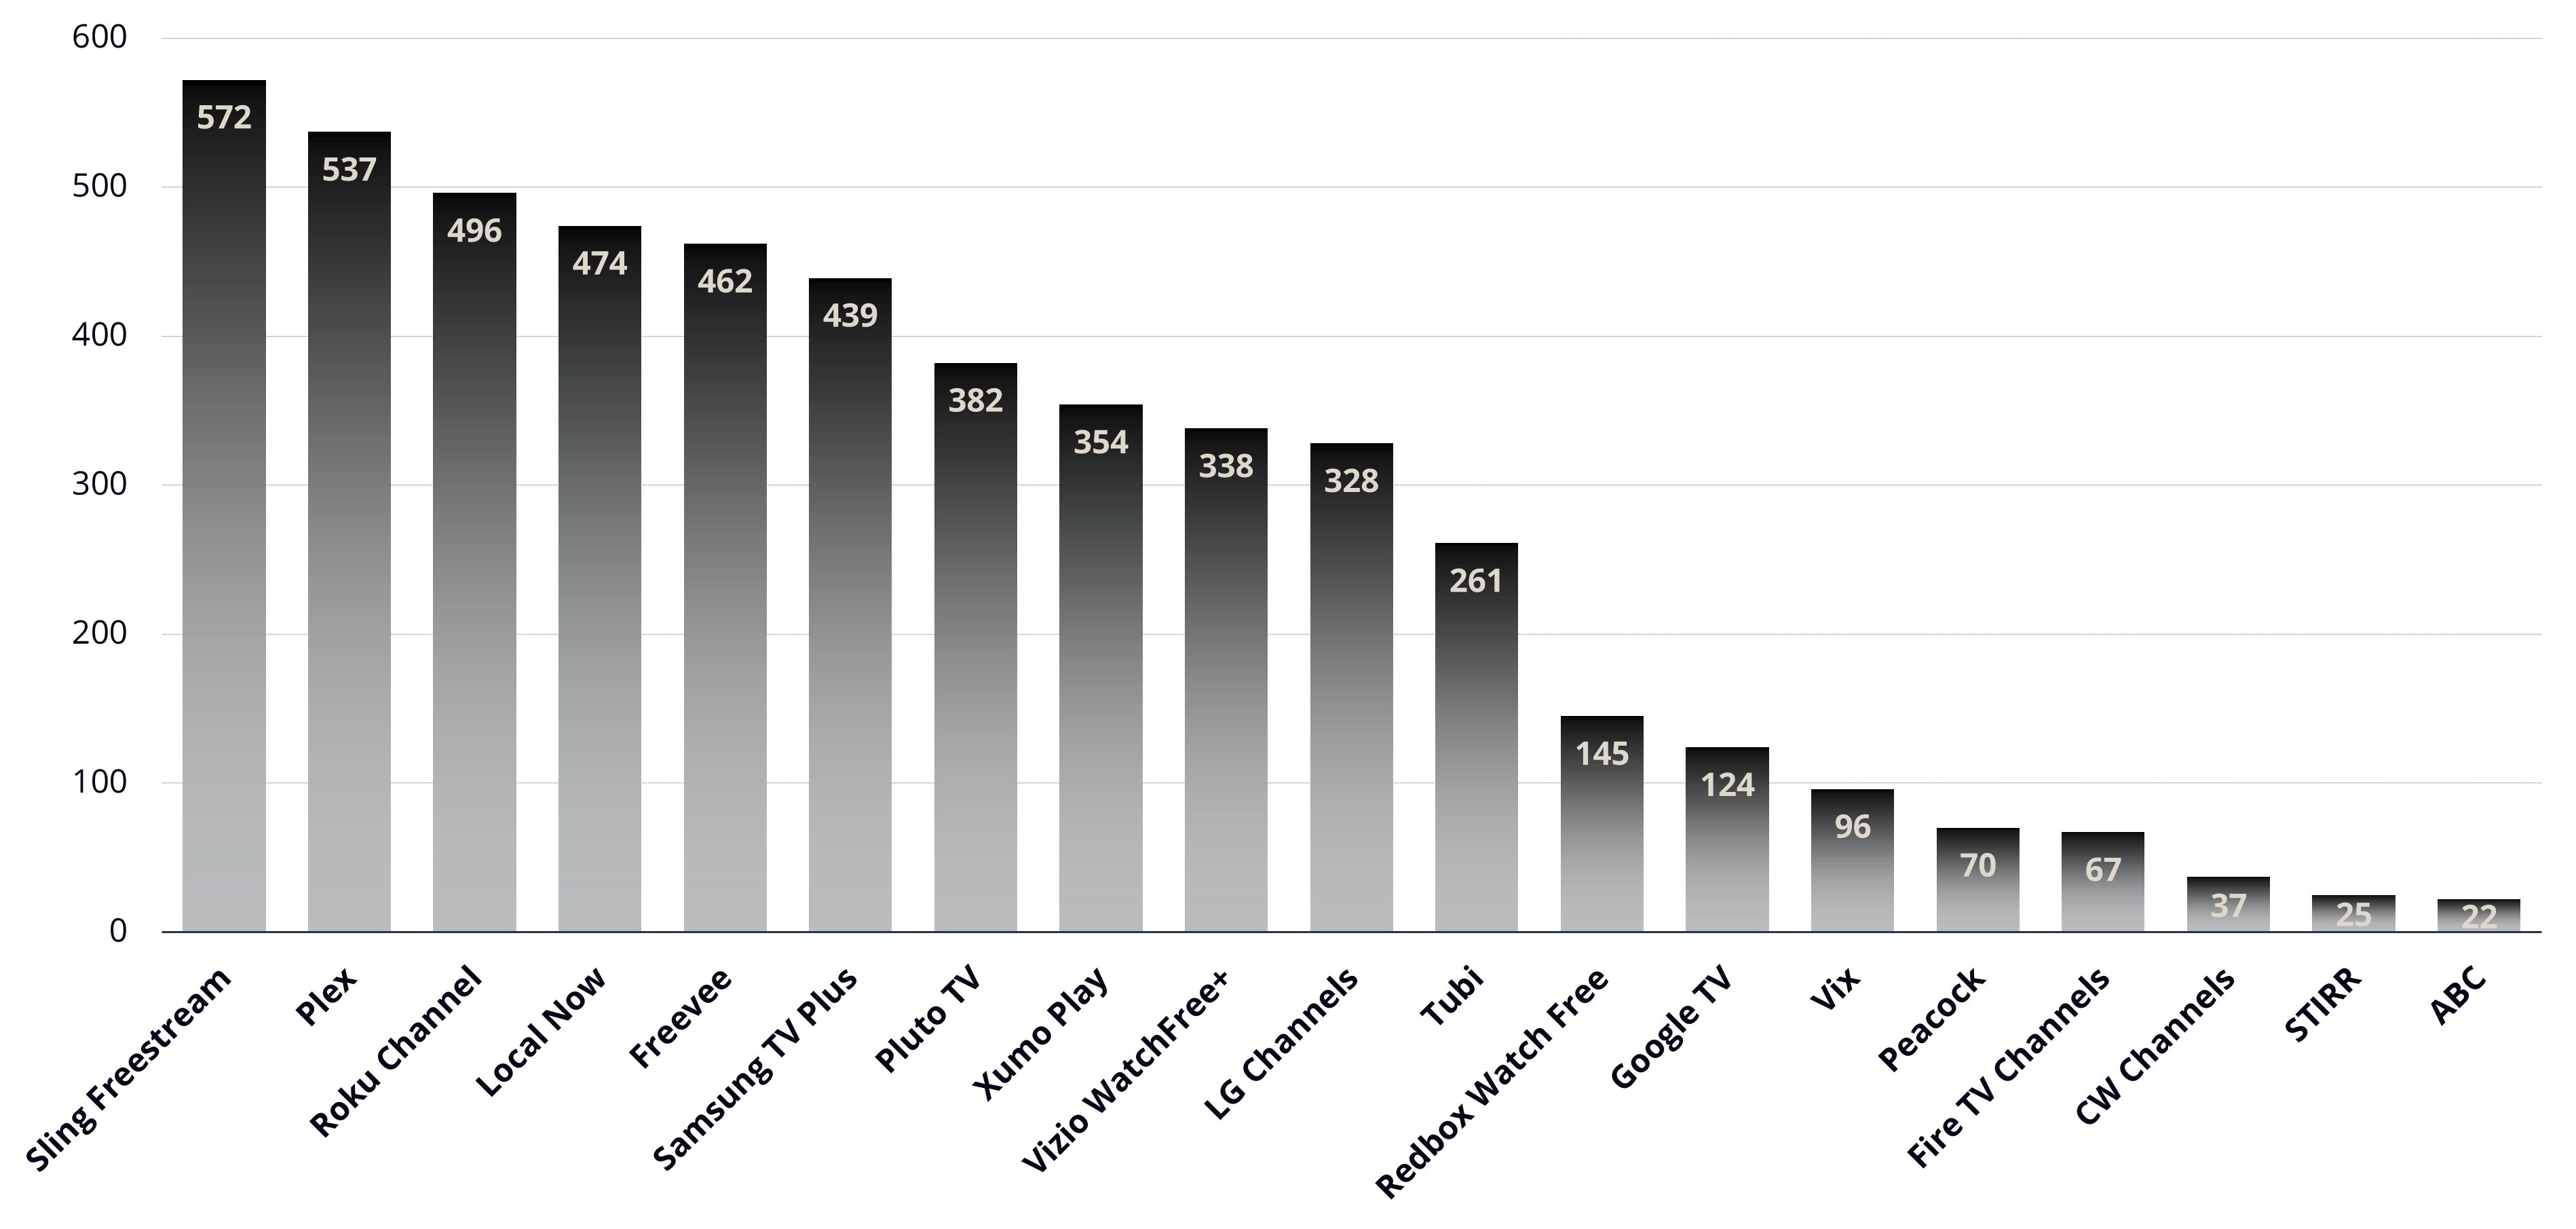
I found it interesting to note that Vix removed a number of channels and shrunk in total output. It does make me wonder if Spanish-language content has maxed out, especially given the slight dip total channels has seen in trends for a few months now.
Google TV added a few more channels to its native app. If there ever was a sleeping giant, it would be one of the Google services (YouTube where are you?) in FAST. So for now let’s all be happy that they’re sleeping on it.
Tubi redid their EPG with the rebrand, finally deciding that having one genre for “enterainment” was a bit weird, as was just sticking all the WB TV channels one after the other and not by genre. Now Tubi has genres like everyone else (“food”, “classic TV” etc.). They are also doing a geo-location thing to limit the local news channels that users see. At least that’s what they told me when I reached out to ask what was up with local news, but when I saw the channels that are apparently “close” to me in New York, I had ones from Los Angeles and other cities much further away than places like North Carolina, Baltimore etc. So IDK what’s up there.
Also worth noting - the first election 2024 channel has launched. Decision 2024 can be found on Peacock. Don’t @ me to say Peacock is not a FAST service, it secretly still is, Peacock just doesn’t want people to know (so they’ll pay). At least that’s the gist of what I was told recently. Bottom line, the channels are still free if you had a login prior to the closing of the gates to new free users, or if you used to pay but cancelled service.
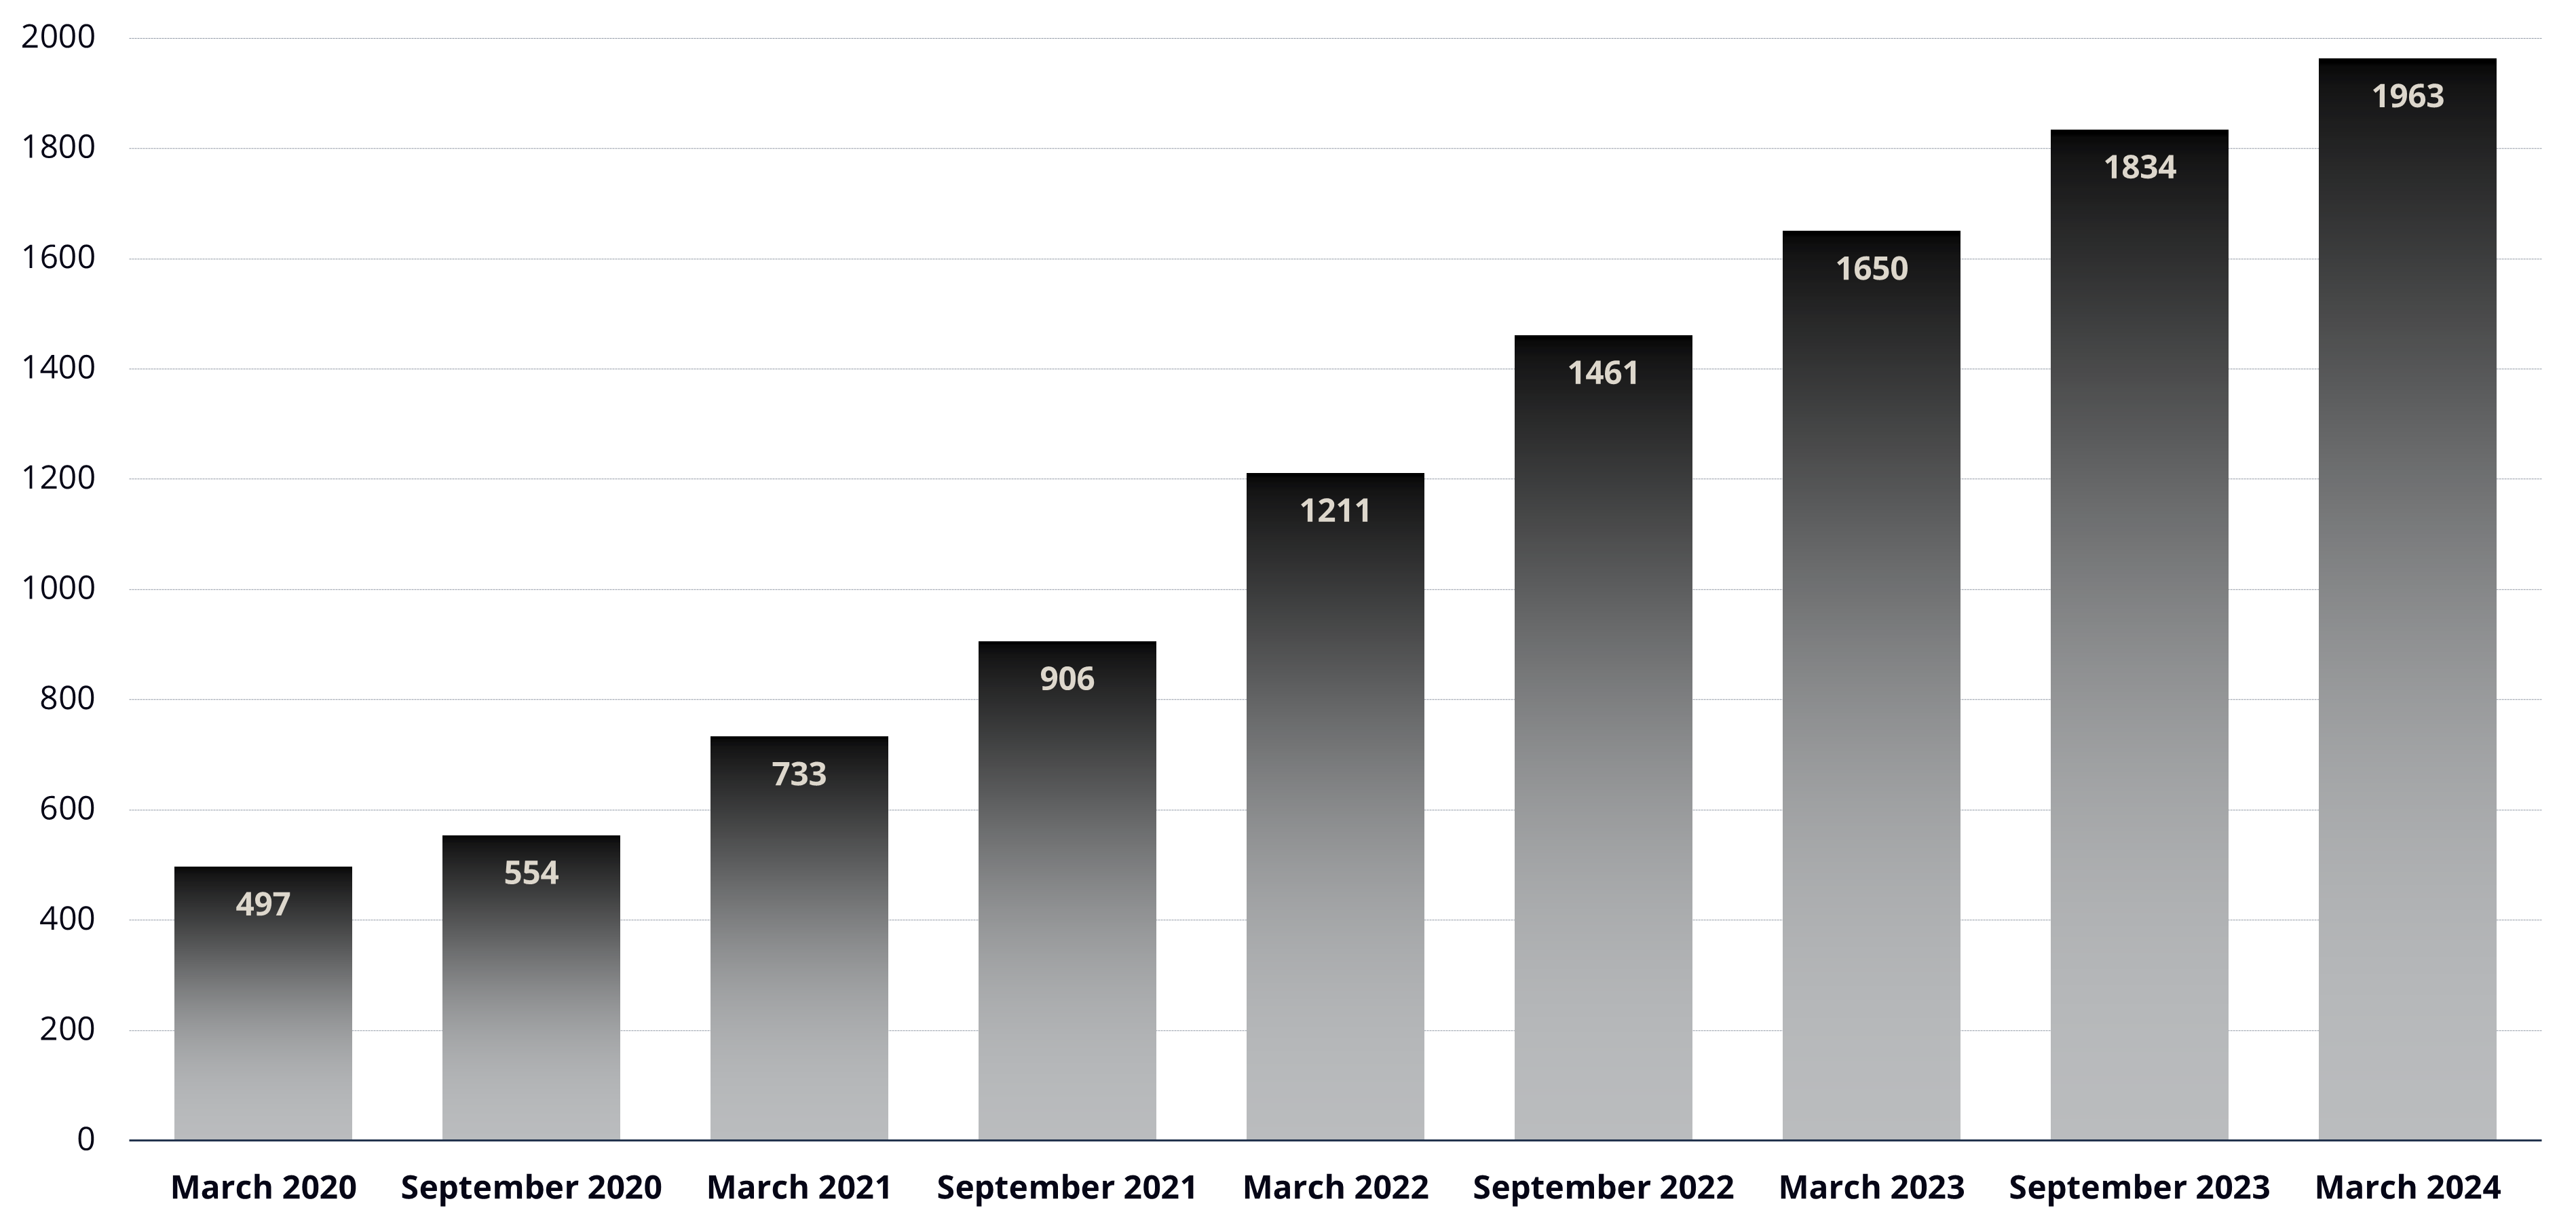
Here’s the chart for the unstoppable rise of FAST channels. Almost 1,500 more in four years is wild but speaks to the success of the format. Growth has slowed recently (March 2023 saw +439 year-over-year vs. +313 YoY this year) but it’s not exactly going from a torrent to a trickle. I think we’ll see this yearly trajectory continue, so I imagine that would mean I need to make a prediction for September 2024. To quote Al Pacino, my eyes see 2,100 channels in six months time.
So that’s the broad overview for the market this month. More to come, as promised, but until then, I will leave you with this tantazlizing AI graphic I generated for one of the sessions I’m doing at TV of Tomorrow which is entitled “Shattering the Myths of FAST”. Might have to turn it into a report after.
(Who doesn’t love a good Gustave Dore-inspired woodprint?)
Thank you for reading. Any questions, feel free to reach out: gavin@fastmasterconsulting.com.